Skip to content
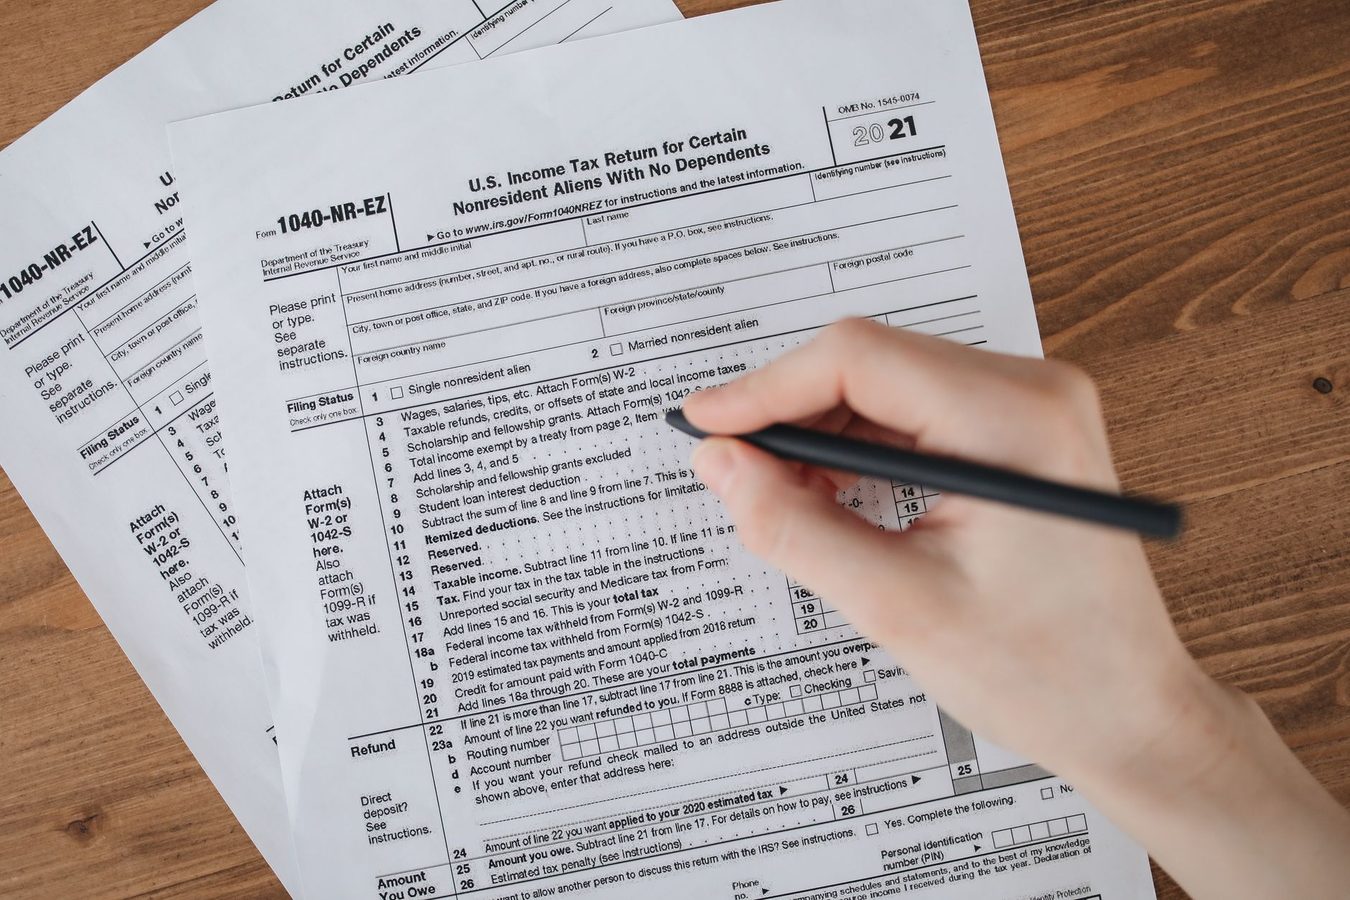
A person working through printed tax paperwork at a desk with a laptop and pen
Myths versus facts

What Tax Residency Really Means

An independent, plain-language briefing on how the United States decides who is a resident for federal tax purposes, what the substantial presence test actually counts, and which income records are worth keeping from January onward. Explanations only — no personal determinations.

The lead article

Four Beliefs About Residency That Quietly Cause Paperwork Problems

A stack of paper income statements and tax documents on a wooden desk
Most residency confusion starts with documents that were never sorted in the first place.

The lead articleUpdated September 2026

Myth: your visa category settles your tax status

An F-1 or J-1 stamp in a passport is an immigration document. It tells a consular officer and an inspector at the port of entry what a person is permitted to do in the country. It does not, on its own, tell the Internal Revenue Service how income is taxed. Federal tax residency is decided by two statutory tests — the green card test and the substantial presence test — applied to a specific calendar year. That is why two people holding the same visa category, arriving in different years, can end up filing different forms. A careful sprintax calculus overview usually opens with the same reminder: tax residency and immigration status are separate ideas, written into different parts of federal law, and a change in one does not automatically move the other.

The substantial presence test counts days of physical presence in the United States: every day in the current year, one third of the days in the prior year, and one sixth of the days in the year before that. If the total reaches 183 and the person was present at least 31 days in the current year, the test is met. Certain people — students, teachers and trainees in particular categories — may exclude days as exempt individuals for a limited number of years, which is where the arithmetic stops being simple. Institutional questionnaires exist largely to automate that counting, and a sprintax calculus substantial presence test screen is usually just a structured way of asking for entry and exit dates, visa history and prior visits, then applying the same published formula by hand-checked rules.

Myth: the questionnaire and the tax return are the same thing

Ask around a campus international office and you will hear two names used interchangeably. They are not the same. The short answer to what is sprintax calculus is that it belongs to the category of residency-determination and withholding questionnaires that universities, research institutes and employers use before money is paid out. It sits at the start of the year, on the payroll side. Return preparation software sits at the end, after the calendar year closes. The difference between sprintax calculus and returns is therefore a difference of timing and purpose: one helps a payer decide what to withhold and which statements to issue, the other helps an individual report what already happened. Confusing the two is the most common reason someone believes a filing obligation has been handled when it has not.

With that split in mind, how does sprintax calculus work in practice? Sprintax calculus explained at its simplest is a sequence of questions: personal details, country of residence, visa and entry history, the dates of every US arrival and departure, the type of payment expected, and any treaty claim the person believes applies. From those answers the tool applies the residency tests and produces the payroll paperwork the institution needs — commonly withholding certificates, treaty statements and cover documents to sign and return. Nothing in that process determines anyone's status independently; it organizes facts the individual supplies and applies published federal rules to them.

Myth: nothing matters until filing season

The records that make spring straightforward are collected in the previous twelve months, not in April. A working sprintax calculus document checklist is really a personal filing system: passport biographic page, all visa stamps and I-94 travel history, the immigration document tied to the current program, a Social Security number or ITIN if one has been issued, offer or appointment letters, and every income statement received. Sprintax calculus required documents overlap almost exactly with the paperwork any international filer should keep anyway, which is the useful part of the exercise even for people whose institution never asks them to complete one. Questions about how to use sprintax calculus usually turn out to be questions about where a specific date or document number can be found.

A sprintax calculus profile guide, in the neutral sense, is simply the habit of keeping that profile accurate: dates entered correctly in month/day/year order, travel logged as it happens rather than reconstructed later, and a note whenever a program end date or funding source changes. A sprintax calculus questionnaire guide is the same discipline applied to the answers themselves — reading each question as written, and not assuming that last year's response still describes this year's situation. The federal tax year for individuals runs from January 1 to December 31, and residency can change between one year and the next, so the record has to be rebuilt annually rather than copied forward.

Myth: a tax treaty applies automatically

The United States has income tax treaties with dozens of countries, and several contain articles covering students, teachers and researchers. None of them apply by themselves. A treaty position generally has to be claimed, documented and accepted by the payer before withholding changes, and the article, the country and the type of income all have to line up. That is why sprintax calculus tax treaties questions are really payroll questions: the answer determines what appears on a withholding certificate, and sprintax calculus tax withholding outcomes follow from the residency determination made first, not the other way around. The forms that result — the statements and certificates a payer keeps on file — are ordinary sprintax calculus tax forms, not a substitute for any annual report an individual may owe.

The audience for all of this is broad. Sprintax calculus for international students tends to focus on exempt-individual years and campus employment. Sprintax calculus for international employees is more often about treaty articles and payroll setup, while sprintax calculus for visiting scholars sits somewhere between the two, shaped by program length. Sprintax calculus for non residents, as a phrase, simply describes the situation of anyone the tests classify that way for the year in question. And sprintax calculus for beginners means starting with vocabulary rather than software. This site keeps a plain sprintax calculus guide, a sprintax calculus user guide to the terminology, and a running set of sprintax calculus frequently asked questions — all of it educational, none of it a determination of any individual's status.
Side by side

What People Assume, and What the Rules Say

Common beliefWhat the published rules actually sayWhy it matters for your records
My visa category tells me whether I am a residentResidency for federal tax purposes rests on the green card test and the substantial presence test, not on visa typeKeep entry and exit dates for at least the last three calendar years
Residency status is the same every yearEach calendar year is tested on its own, and a status can change from one year to the nextRebuild the day count annually instead of reusing last year's answer
The residency questionnaire also files my annual reportA sprintax calculus residency determination supports payroll and withholding; the annual return is a separate stepSave the questionnaire output and the year-end statements separately
A treaty from my home country applies automaticallyTreaty benefits generally have to be claimed and documented before a payer adjusts withholdingKeep copies of any treaty statement or certificate you signed
Students never count days of presenceExempt-individual treatment applies only to certain categories and only for a limited number of yearsNote the first year of each program, not just the current one
Only payslips count as income recordsYear-end statements, scholarship notices and payer-issued forms all belong in the fileStore every form you receive, even one you think does not apply
The tax year can start whenever I arrivedFor individuals the federal tax year runs January 1 to December 31Date every record in month/day/year order to avoid mismatches
Four Common Myths

The Same Rules, Seen From Four Angles

The myth is that every student on an F-1 visa is automatically a nonresident forever. In fact, the exempt-individual rule that excludes certain days from day-counting generally applies for a limited number of calendar years, after which the substantial presence test begins to apply normally. Material describing residency questionnaires, including a sprintax calculus overview, usually explains this exempt period rather than granting it. A sprintax calculus guide is reference reading, not a ruling on your status.

Many international employees assume payroll withholding settles the question of residency. It does not. Withholding is an advance payment applied by an employer using the information on file; residency classification is determined separately under federal tax rules for the tax year in question. When people ask what is sprintax calculus, the short answer in an educational sense is that it names a category of residency and withholding questionnaire tools used by institutions, not a tax authority.

Visiting scholars often believe a short stay cannot create residency. Day counts accumulate across years under the substantial presence test, and a J-1 research category has its own exempt-year limits that differ from student categories. Reading a sprintax calculus for visiting scholars explainer alongside IRS Publication 519 is more useful than relying on department folklore. Neutral material on sprintax calculus tax residency describes the counting method; it does not decide the outcome for you.

The most persistent myth is that documents matter only in filing season. Income statements arrive in January and February, but the records behind them — entry and exit dates, visa category changes, treaty claim paperwork — are created all year. Any sprintax calculus document checklist you encounter is essentially a prompt to keep those items together. A sprintax calculus required documents list works best as a filing habit, not a March scramble.

Questions We Get

Frequently Asked, Frequently Misunderstood

What is sprintax calculus in plain terms?

It is the name of a residency and withholding questionnaire product used by some universities and employers to collect information from international payees. On this site the phrase appears only as terminology a reader may encounter. A neutral sprintax calculus overview describes what that category of tool collects — travel history, visa category, income type — and nothing more. We do not supply, endorse, or operate any such tool.

How does sprintax calculus work compared with a tax return?

The difference between sprintax calculus and returns is a difference of stage. Residency and withholding questionnaires are generally completed before or during the year, so an institution knows how to treat payments. A tax return is filed after the tax year ends and reports what actually happened. Asking how does sprintax calculus work is really asking how a pre-payment questionnaire differs from an annual filing.

Does my visa category decide my tax residency?

No, and this is the myth we correct most often. Immigration status and tax residency are governed by separate bodies of federal law. A person can hold a nonimmigrant visa and still be treated as a resident for tax purposes under the substantial presence test, or hold long-term status and be treated otherwise. IRS Publication 519 sets out the classification rules independently of visa category.

Where do I start if I have never counted days before?

Start with the calendar, not the software. The substantial presence test counts all days of US presence in the current year, one-third of the prior year's days, and one-sixth of the year before that. Any sprintax calculus for beginners explainer restates that arithmetic. Reading a sprintax calculus substantial presence test description helps, but the underlying rule lives in the Internal Revenue Code and the IRS instructions.

What documents should I keep during the year?

Typically your passport stamps or I-94 travel history, immigration documents such as an I-20 or DS-2019, Social Security or ITIN records, and the income statements you receive — Form W-2, Form 1042-S, or a Form 1099 series document. A sprintax calculus questionnaire guide will ask for much the same material. Keeping it in one folder is a recordkeeping habit, not a filing product.

Do tax treaties automatically reduce what is withheld?

Not automatically. Treaty provisions between the United States and another country may apply to certain income types and often require a claim, usually documented on Form 8233 or Form W-8BEN, with a taxpayer identification number. Discussions of sprintax calculus tax treaties describe where such claims are recorded. Whether a provision applies to you depends on treaty text, residency, and the nature of the payment.

Is this site telling me how to use sprintax calculus?

No. We explain vocabulary. Questions about how to use sprintax calculus, or requests for a sprintax calculus user guide, should go to the institution that issued your access — a university payroll office, an international student services team, or an employer. We are an independent educational publication with no affiliation to any provider, and we cannot see or assess your individual records.

Who determines my status if a questionnaire cannot?

Ultimately, federal tax law does, as applied to your facts. An institution may make a withholding decision based on what you report. The IRS may reach its own conclusion when a return is filed. If your situation involves dual status, a treaty claim, or a mid-year change, a credentialed tax professional is the appropriate place to take it.

Where Facts Come From

Sources We Read Before We Write

Behind The Copy

Who Writes and Checks These Pages

Managing Editor

Editorial standards, myth corrections, tax-year labelling

Sets the rule that every claim names its source and its applicable tax year. Reviews each page for language that could be read as personalized advice and rewrites it into plain explanation.

Research Reader

Primary-source checking against IRS publications

Traces every statement about day counting, treaty claims, or reporting documents back to the published instruction or code section it came from, and flags anything that only exists in secondary commentary.

Terminology Writer

Glossary entries and product-name explanations

Drafts neutral definitions for terms readers arrive with, including the sprintax calculus explained material, so a name encountered in a payroll email becomes a category a reader can understand.

Accessibility Reviewer

Reading level, structure, and screen-reader clarity

Tests pages for plain-language reading level and logical heading order, so someone reading in a second language can follow a residency explanation without a legal dictionary open beside them.

Read the Rule Before You Read the Rumour

Most residency confusion comes from advice passed between classmates and colleagues. Start instead with what the published rules actually say about tax years, day counting, and the records you keep.